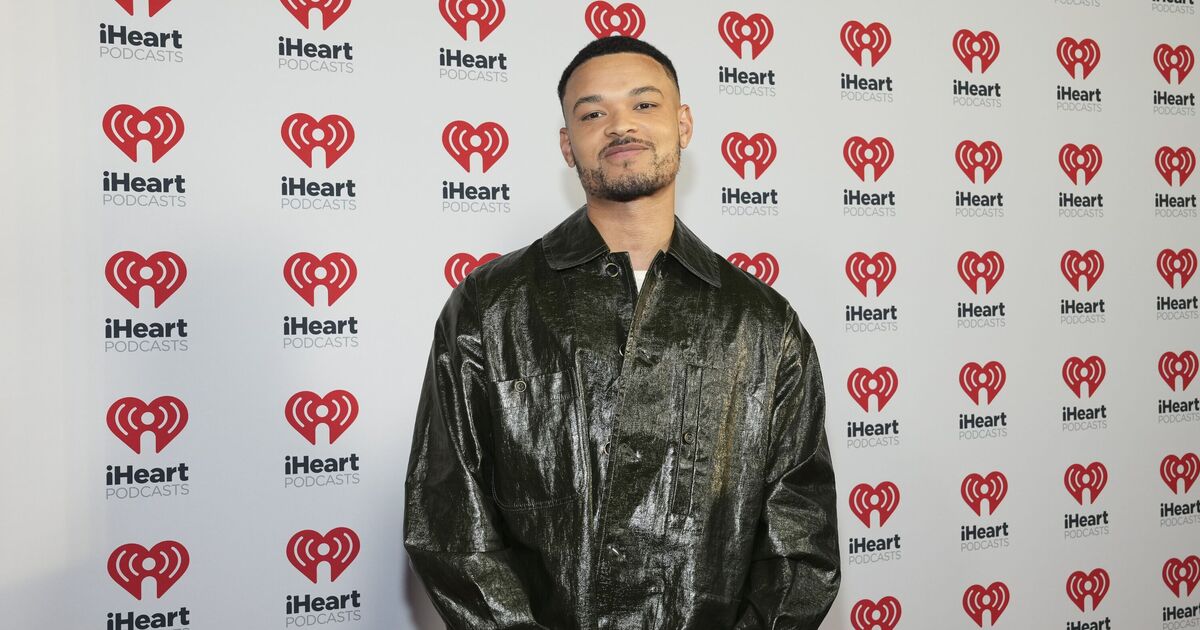

Steven Bartlett, known for his role on Dragons’ Den and his popular podcast, The Diary of a CEO, recently sparked a surprising reaction when he asked three top financial experts if it’s a “terrible idea” to get a mortgage to build wealth. In a recent episode, Steven spoke with finance gurus Raoul Pal, Jaspreet Singh, and Humphrey Yang.
Steven referred to an article he had read which suggested that ‘more millionaires are now renting in the US than ever before.’ With the number reportedly tripling between 2019 and 2023, he asked the experts to shed light on this trend. This led to a discussion about the pros and cons of renting versus buying. Humphrey suggested that some people choose to live on the US coast because they often invest or have high-paying jobs, but it could still be “slightly unaffordable” to buy property in places like New York or Los Angeles, even with a good income.
Steven mentioned that the article claimed these individuals are choosing “flexibility and liquidity” over ownership and don’t want to deal with the “inconveniences” of owning property. Later, he questioned whether buying a property to generate wealth was a “terrible idea”.
He explained that growing up, everyone told him that the path to follow was to get a job, save money, and then get a mortgage – it was just something that people did.
Jaspreet retorted that it was “one of the worst” pieces of advice you can give someone, to which Steven countered that it’s what everyone is doing, and continues to do.
Steven observed that his mates also follow this path: “The first thing they do when they get a bit of money is go and get a mortgage, because that’s what their parents did and that’s what everyone’s always done. Is that a good idea?”
Raoul’s answer was a “yes and no,” highlighting that the economy is different now compared to when he was 25 and purchasing his first flat in London. He pointed out that back then, he would have had to pay 3.5 times his income for a property in the capital, but claimed an equivalent now is 12 times, so renting “makes much more sense now.”
He further stated that a person’s main house isn’t an investment, as you tend not to sell it once you own it although it could be an investment in “your future.”
Steven characterised the concept as an “optical illusion,” where you believe any money spent on rent will never be seen again, while paying into a house you own is akin to depositing your cash into a piggy bank.
Jaspreet argued this isn’t “exactly true.” He went on to provide an example of buying a $500,000 (£367,000) house, putting down 20 per cent ($100,000 / around £73,000) and financing $400,000 (£294,000) with a 6.5 per cent mortgage over 30 years.
He said he’d pay $2,500 (£2,836) a month and build equity in his property (the amount of the property you own), but banks “understand the same game” and “frontload the payments” on your mortgage.
Jaspreet explained that when he pays his $2,500 (£918), it’s not $1,250 (£918) “going to principal” (buying it back) to build equity in his home and $1,250 towards interest—it’s “almost all” interest.
Referring back to his theoretical house purchase, he observed that during the initial 20 years, more than half the payment will go straight to the banker through interest, and it’s only upon reaching year 21 that half the payment will be allocated towards equity.
Nevertheless, throughout the years, many individuals will experience changes in interest rates, so they may choose to refinance, and then the amortisation process begins anew, meaning he must pay interest once more, and the “real equity” that he’s been accumulating is simply “not there.”
Jaspreet added: “This is why I say it’s not bad to buy a house. I think it’s great if you buy a house, but don’t treat your house like—like you said—don’t treat your house like an investment. Treat it like an expense.
“Buy it because you can afford it, because you want it, because you’re ready, but not because you’re going to build wealth.”
Chiming in, Humphrey added that he agreed with both perspectives.
